Friday, 25 March 2016

Financial Passage Maker - March 2016 Edition

March 2016

The Financial Passage Maker

The Voyage

1.    The Financial Log Book

The table now shows the relative weightings of holdings in the portfolio.

2.    View From the Masthead

I figure that it is time for caution: the first rule of investing according to Herr Buffet is “not to lose money” ... ditto for the 2nd and 3rd rules. Prem Watsa has penned a cautionary outlook in his annual letter to shareholders.

3.   View From the Gun Port

No new purchases with the exception of short-term speculative ventures in gold companies. I have increased my stake in a few companies.

4.    Recommended Reading for the Moorings

The Big Book of Endurance Training and Racing by Dr. Philip Maffetone is well worth reading, especially by people who are interested in functional bodies.

5.    In the Wake

A substantial review of my portfolios is underway in preparation for what I consider will be “interesting times” ahead.  (See also View From the Masthead.)

Investments are only an enabler for the most important things in life: family, friends, health, travel, music (more on that in a future newsletter) and all manner of learning and exploration.


1.    The Financial Log Book 


Entity
Wt
Initial Price/ Purchase * Date Price *
March 24/16
Gain/Loss
since Jan 1/16
%
Gain/Loss
Since Purchase
%
Silver Wheaton
(SLW)
H
12.37
2007-09-04
22.82
32.7
84.5
Polaris Materials Corporation (PLS)
L
10.70 **
2007-06-01
1.5
-2.6
-85.9
Cenovus (CVE)
M
32.39
2010-07-27
16.89
-3.5
-47.8
North West Company (NWF)
H
16.23
2009-05-07
29.26
3.2
80.3
Deere & Company (DE)
M
88.07
2013-01-03
80.24
6
-8.9
Rocky Mountain Dealerships (RME)
M
11.89
2013-01-03
5.81
-6.9
-51.2
HollyFrontier (HFC)
M
47.95
2013-01-28
35.33
-10.6
-26.3
Oak Tree Capital Group (OAK)
M
56.45
2013-10-28
46.93
-0.7
-16.8
Fairfax Financial Holdings (FFH)
H
477.98
2014-3-25
715.9
11.2
49.8
Clean Seed Capital (CSX)
L
.51
2015-01-07
0.49
-21.9
-3.9
Abitibi Royalties (RZZ)
M
2.57
2015-11-20
3.65
8.8
42
Input Capital (INP)
L
1.86
2015-11-20
1.63
-8.4
-12.4
Marquee Energy (MQL)
L
.49
2015-11-23
0.39
0
-21.3
Fairfax India Holdings Corp (FIH.U)
M
10.42
2015-12-16
10.59
4.9
1.6
CRH Medical Corp (CRH)
L
4.43
2105-12-29
4.18
1.9
-5.6

*    Prices are quoted in the currency of the exchanges where equities are listed.  As a result the gain/loss is not an accurate measure of the performance of the portfolio as the $US has risen significantly against the $=Cdn since many US positions were established.
** does not reflect impact of a large follow-on investment @ $.67 per share

A new feature is an indication of the relative weightings of holdings in the portfolio:
H = >10%
M = 5-10%
L  = <5%

In general, my strategy is to invest relatively small amounts in small, fledgling enterprises and then to increase/decrease my stake on the basis of performance.

Not shown on the chart is an old favourite, Questor Technology Inc, my first ten bagger.  I sold it off for a great profit but have renewed and gradually increased my position.  I am hopeful for a nice profit as the company's new offering makes its way into the market.  It's always nice to see a company able to finance acquisitions and product development without recourse to debt.  The stock was crushed when oil prices declined but its value is now being recognized by the market.  Questor's recent performance has been gratifying.  I figure that the good times will roll once again. Read more about it here:
http://www.questortech.com/

Agriculture

The depressed $Cdn has increased the effective cost of American-made equipment prices for Canadians.  This, coupled with farmers' reluctance to spend cash for new equipment in the face of challenging commodity markets, has had an impact on new equipment sales.  The share prices of Deere and Rocky Mountain Dealerships have been affected negatively.   In my view, the current state of pessimism represents an opportunity to secure additional shares on the part of investors with the longer view.  Both companies are very well managed and have been through the peaks and valleys of the agricultural commodity cycle before.  Analysts with shorter time horizons seem to ignore this history ... and market “talking heads” are even worse ... seems as if ADD is a requirement for market commentators.

It will pay to wait for the cycle to repeat itself.

  • There are more mouths to feed in the world.
  • The demand for grains will increase as a result of growing global prosperity and the role of grains in the diets of affluent societies.
  • The spectre of greater variability in crop performance in the future due to climate change will probably be beneficial to farmers in most of Canada's producing areas – this in comparison to other parts of the world where droughts and floods are likely to be more severe.
  • In some parts of the world, such as India and California, the mismanagement of water supplies and competition for water presents substantive challenges to the viability of traditional agriculture, thus opening the possibility of new opportunities for Canadian farmers.
  • Socio-political strife and massive corruption in places such as Brazil has the potential to disrupt the movement of agricultural products to world markets.  

I have increased my stake in Input Capital (INP).  Read the following third quarter report to see why:
http://s1.q4cdn.com/784243260/files/doc_news/Input-Capital-Corp-Announces-Fiscal-2016-Third-Quarter-Results.pdf

Investors in new companies must be prepared for inevitable up's and down's in performance.  Sometimes, people over-react to setbacks.  A few months ago, the price dropped due to concerns about a few streaming contracts which had gone south.  The company adjusted its practices very quickly and achieved some positive results thereafter as noted in the third quarter report.

In my view, the most significant challenge ahead for INP is how it develops a strategy to sell its streams into an “interesting” commodities market.

The Oil Patch

The following commentary by Leonardo Maugeri provides a sobering perspective on the current state of the oil industry.  The Global Oil Market: No Safe Haven for Prices

Despite the decline in price, actual production of oil seemed to defy the laws of gravity and economics as it continued to grow. Once again, the main reason for this apparent contradiction is that while many companies and countries announced cuts to their spending budgets, very few actually halted investments already under way in the upstream sector. Many are just beginning to register production from recently completed investments, while others are completing their investments, after having spent the bulk of their capital budgets. The result: production capacity and the supply of oil will continue to grow.

... the conclusion?

... unless demand growth actually explodes—which seems unlikely—the fundamentals remain the same: in spite of some erosion of production here and there, global oil output, production capacity, and inventories will remain too high versus the level of consumption growth. This implies that the downward pressure on oil prices will remain the dominant force in 2016, with the first real inflection point for the market, which could probably materialize only in 2017.

I think Maugeri may have underestimated the potential for geopolitical uncertainty to destabilize oil production and transport, especially in the Middle East.  To my mind, it remains as the wild card.

Also, the industry is cyclical.


I don't believe for a moment that the world will wean itself off oil any time soon.

  • The infrastructure for discovery, extraction, transportation, distribution and use is very well developed.  Competing sources of energy lack this infrastructure and it will only be developed at the considerable expenditure of time and money.  The fossil fuel system is reliable – the product of over a century of trial and error.
  • Businesses and other energy consumers are by nature conservative: risk adverse to new technologies, set in their ways and generally with no compelling reason to change.
  • Other than the possible exception of solar-generated electricity, other non-fossil fuel technologies generally have had major challenges: higher than anticipated all-in costs, confusion caused by a plethora of competing emerging technologies without any clear leader.

The shift in the mix of power sources will be evolutionary rather than revolutionary.  There are still rewards ahead for investors who recognize this circumstance.

Precious Metals

Speculative activity has been very profitable in the face of an increase in the price of gold and silver in recent months.  I've learned to take profits of 3 to 20 percent as opposed to hanging on for more.  As a result, I have made a nice series of “base hits” by making short-term bets in several companies:

Dalradain Resources
Goldquest Mining
Asanko Gold
Premier Gold Mines
McEwen Mining
Oceana Gold

The market action has been fairly choppy, a circumstance which presents opportunities for short-term speculation.

http://www.kitco.com/charts/popup/au0365nyb.html

The long-term trend for gold is somewhat ambiguous.  I believe that its price is a barometer of fear and  an indicator of the value people place on its utility as a safe haven in the face of geopolitical uncertainty and misgivings about the “true” worth of fiat currencies.

http://www.kitco.com/charts/popup/au3650nyb.html

History tends to repeat itself.  In light of this, and as a form of “speculative insurance”, I have maintained some long-term core holdings, mainly in streaming companies:

Silver Wheaton
Franco-Nevada Corp.
Abitibi Royalties

The last company, RZZ, has been a very pleasant surprise.  Its business model is rather novel and has yielded some nice profits by focusing on an under-serviced niche in the industry.  Its focus on spending bits of its grubstake on properties adjacent to active mining operations has parallels to the strategy of McEwen Mining ... no surprise given the work history of Ian Ball (a McEwen protegee) and the significant position McEwan holds in Abitibi.  Check out the website of RZZ to see how its net smelter royalty interests are benefitting its bottom line.  It's only a matter of time before imitators start to enter the fray.  Meanwhile, Abitibi has the advantage as a first entrant.  It's all about management – in this case, Ball and McEwen ... nice to see the fusion of olde and newe talent working to realize a new business model.

Abitibi represents a model with two desirable attributes:

a play on the potential development of mining claims adjacent to producing properties
a play on the possibility that gold prices might increase in the future as reflected in the value of net smelter royalties

The odds of encountering an Eldorado are low, but the potential pay-off's could be substantial ... and the cost of Abitibi's individual bets is exceptionally low.  All in all, a good business model for this sector, especially at this time.


2. View From the Gun Port

Arotech – The Saga Continues

Activist investor, Ephraim Fields of Lake Capital, continues his quest to change management practices and the composition of the board.  On February 23, 2016 he sent a letter to the Board of Directors of Arotech about recent decisions on the part of the company in which he:

- Criticizes selling 5.7% stake at below market prices to "friendly" shareholder
- Criticizes failure to mention Consulting and Voting Agreements in press release
- Questions Board entrenchment nature of the financing
- Believes effective sale price significantly below $1.99 per share
- Questions need to pay up to $375,000 in "consulting fees"
- Pleased with the addition of Jon Kutler to the Board
https://www.accesswire.com/436975/Ephraim-Fields-Criticizes-Recent-Arotech-Financing
The latest salvo follows on the heels of an earlier letter which made the following points:
- Stock has significantly underperformed; down 29% in one year; down 76% over the past 10 years.
- Believes Training/Simulation unit (which generated $9.5 million of LTM EBITDA) alone is worth more than ARTX's entire enterprise value.
- Over the past 15 years the Company has paid Ehrlich and Esses combined compensation of over $25 million, which equates to over 60% of Company's current market cap.
- Believes corporate overhead is too high and can be easily reduced.
- Believes there are many, readily identifiable ways to create long-term shareholder value.
- Believes alternate slate is in best interests of ARTX's shareholders, employees and other stakeholders.
- Notes the price paid for just the UEC and Armour acquisitions exceeds Company's current enterprise value.
http://www.theglobeandmail.com/feeds/press-releases/accesswire/?pr=600-201512100801BAYSTRETCA_DIS_T_NW_434551-1

It will be interesting to follow this story.  As the election of Board members is staggered over a 3-year period, it will be difficult for Fields et al to force what I consider would be some useful changes in Arotech's business practices.  There have been some recent changes in the Board which may hold some promise for positive change over the longer term (check the company's web site).  I am quite prepared to wait as I feel that the company has some noteworthy attributes which have the potential to be reflected in a higher stock price in the future ... provided that senior management approaches life in a manner which respects more fully, the interests of share owners.  In the meantime, simply the knowledge that people are looking over one's shoulder sometimes changes behaviours.
The year-to-date performance of Arotech has been gratifying ... perhaps a harbinger of the spring to come?

3. View From the Masthead

I have some misgivings about the future of the global economy and will comment on this at length in a future edition.

The key in investing is not to lose money.

Prem Watsa embraces this approach.  Here is what he has to say in the most recent annual Shareholders' Letter for Fairfax Financial Holdings Limited:

Hedging our common equity exposures has been very costly for us over the last five years – particularly in 2013. However, we have warned you many times in our Annual Reports of the many risks that we see and the great disconnect between the markets and the economic fundamentals. These risks may be coming to a head in early 2016, as I write this Annual Report to you – right out of the blue! The most important risk we saw was that the 2008/2009 recession was not like any we had experienced in the last 50 years. The closest comparables were the U.S. in the 1930s and Japan since 1990. Most investors consider the 2008/2009 recession and crash to be a once in a generation event – and it’s over! We differ because we think we escaped the serious adverse consequences of that recession as a result of huge fiscal stimulus from the U.S., even greater fiscal stimulus from China and the reduction in interest rates to 0% with massive monetary stimulus in the U.S., Europe and Japan through QE programs. There is nothing to fall back on now if the U.S. and Europe slip back into recession. Here are some of the risks we discussed in our recent Annual Reports:

I would urge everyone to read the report in its entirety and to pay special attention to pages 17 and onward.
http://s1.q4cdn.com/579586326/files/doc_financials/2016/2015-Shareholders'-Letter.pdf

Two members of the Fairfax family constitute a significant part of my portfolios for two reasons:

My confidence in the acumen of Watsa and his team.
The long-term promise of India.

4. Readings for the Moorings 

The Big Book of Endurance Training and Racing by Dr. Philip Maffetone
https://www.amazon.ca/The-Book-Endurance-Training-Racing/dp/1616080655
I have always led a very active life.  In my teens, it revolved around getting to the end of the swimming pool before all others.  However, there was more to life than endless hours of bouncing off walls and churning through the water.  And so, I moved on to other things, most of which entailed sustained physical effort over prolonged periods of time: extended wilderness canoe trips, long bicycle rides including a transcontinental ride which incorporated the Mormon Trail, walking trips, one of which involved the length of the Camino de Santiago de Compostela (soon to be repeated), and skiing and snowboarding (the transition from one plank to two took place this year.)
During this activity, I sustained joint and muscle injuries.  I learned to listen to my body, and in many instances, was able to make adjustments on the fly.  In part, this was done by moving exceptionally slowly and paying attention to the most minute feedback as I went through the motions of walking and cycling.  At one point on the Camino, I changed my gait completely and was far more comfortable thereafter.
By chance, I encountered Maffetone's book.  I'm glad I did as it opened a new window of understanding.  Finally, there is was ... an explanation of some of the theory behind why's and how's of sustaining physical effort over long periods of time.  Most important, Maffetone's work is supported by the expression of results in actual practice.

The book is comprehensive.  Check out the Table of Contents here:
https://books.google.ca/books?id=itA3WWidJ9wC&printsec=frontcover#v=onepage&q&f=false

The book's main weakness lies in the lack of references – a major flaw for readers seeking to acquire more detailed information and understanding.

The field of diet and exercise is populated by many born-again messiahs – people who overcame physical challenges by adopting new dietary and life style regimes.  Many refuse to acknowledge competing points of view.  Many approaches are not justified and modified through extensive and prolonged application by many individuals in different circumstances.  Some approaches are rather extreme and have the potential to do major damage to naive disciples. It is a mine field.
I believe that Maffetone's approach is solid  His book resonated with my years of personal experience. I am now exploring new avenues of learning – to the point where I now wear a heart monitor and am training to build up my cardio-vascular fitness. Maffetone advocates a “gentle approach” - a marked contrast to the “no pain – no gain” attitude which characterizes much of today's fitness regimes.

This book is well worth a look, especially by people who are interested in building functional, healthy bodies.

5. In the Wake

I will concentrate on reviewing my portfolios over the next month or two.  The examination is motivated by a concern about the future direction of the market and my interest in holding only very sound companies with the finest, seasoned management and strong balance sheets. I plan to take profits, cut out losing positions which I feel do not have the best of future prospects.  I plan to hold a substantial cash position.  In other words, I'm battening down the hatches.

On the other hand, I will renew my short-term speculative activity, especially with precious metals.  I am also investigating the use of leveraged ETFs and other vehicles to exploit short-term movements in the markets.

My thoughts are gradually being dominated by non-financial matters: a recent trip to Whistler with the family for some snowboarding and skiing (we had an epic powder day which will be remembered for some time to come); a two week very laid back vacation in Eleuthera, a place where the people are very welcoming and relaxed.  The boating season is approaching and the end of a long stint at renovating and old trawler is in sight.  I've learned that it is cheap to convert to solar power to meet our needs while on the hook or tied to shore for extended periods – this as opposed to relying on a gas-powered generator which I'll keep in reserve.  We also use propane for cooking and for powering an instant-on shower which draws water directly from the Bay – what luxury to have almost unlimited warm showers!

Here are a few shots of places which populate my dream time.


Purpose of the Newsletter

The Financial Passage Maker provides ideas for people interested in building wealth.  It is aimed at thinking people who have decided to take on personal responsibility for their financial well-being.

The newsletter is issued more or less quarterly, a reflection of the fact that good investment ideas are not all that plentiful  ... certainly not sufficient to justify a monthly or bi-weekly report.  All ideas presented in this newsletter are ones that I have invested in personally.  I am not interested in filling space with observations on stocks I do not own.  I eat my own cooking.

The Financial Passage Maker chronicles the messy process of building a financial portfolio.  I hope that it will provide some useful insights and enable readers to think critically for themselves.   As in all things, however, the path to financial well-being takes consistent effort coupled with humility and a knowledge of self.  This can only be developed through practice over many years.  My personal voyage to financial well-being has had unanticipated benefits that are worth far more than my balance sheets: new found friends, new perspectives on the world, and a greater knowledge of self.  Further, I am now more able to help others.
The Financial Passage Maker chronicles my voyage in the investment world.  For the most part, it addresses investments which are in the “growth” part of the portfolios I manage.  In no way do I recommend that you base your personal investment decisions on the contents of the newsletter unless you are prepared either to consult a financial adviser qualified in your area of interest or undertake due diligence on the basis of your own research - or both.  Remember, in the final analysis, you are responsible for your own financial well-being.  Would you have it any other way?
The Financial Passage Maker is issued more or less quarterly; however, I make more frequent postings on a blog by the same name.  It can be accessed here: http://finanacialpassagemaker.blogspot.ca/
Some of those postings are included in the e-mail version while others are not.

Saturday, 5 March 2016

Best Weather Forecasting Sites for Outdoors People

I spend a lot of time outdoors, especially on the water where accurate weather forecasts are important.

Here are my go-to sites:

Norwegian Meteorological Institute

The institute provides the public with meteorological services for both civil and military purposes. The institute is to provide services for the authorities, commerce and industry, institutions and the general public for the protection of their interests, for the protection of life and property, for planning and for the protection of the environment.

The YR site provides very reliable marine weather forecasts.  My brother is involved in sailboat racing and this site is preferred in the racing community.

Windfinder

Windfinder is your free to use weather service for kitesurfers, windsurfers, surfers, sailors, paragliders and other wind related activities - find wind, waves, weather, webcams and tides on one website!

I have used Windfinder for many years.  It uses two forecasting models: one for short-term and one for longer term periods.  It has a variety of useful features:

  • very informative graphics which depict forecasts over a variety of time periods
  • current and recent weather for nearby recording stations (wind speed and direction, wave height/period, temperature (water, air), annual wind statistics
  • animated maps which present a regional overview of wind speed and direction over a variety of user-selected time periods
  • a variety of metrics for historical data

These sites offer several supplemental services, including:

  • tidal charts
  • moon phase
  • weather radar maps
In comparison to a variety of other sites, these are not "dumbed down" for general consumption.  

Of course, there are other sites which are designed to provide specialized information for local situations where detailed information is vital for mountain activities such as skiing.  

This complex is one of the most highly rated ski resorts in the world.  I have skied and snowboarded there on two occasions and have been blown away by the variety of terrain.  The setting is magnificent, especially the scenery along the Sea to Sky Highway which runs from Vancouver to the village of Whistler.  

And if you are ever in Vancouver, make sure to visit the Public Market on Granville Island.  

This pedestrian friendly complex is quite unlike Toronto which wasted a fabulous opportunity to redevelop its waterfront.  A former mayor and his cronies promulgated an ugly barrier of condo towers which sealed off the waterfront from the rest of the city ... development at its worst.  Toronto has not been well governed. The following article provides an excellent account of the results of ignorant decision making by neocons such as former Premier Mike Harris whose misdeeds will take decades to reddress.  That Toronto continues to prosper is due to the basic decency of Canadian society - something which enabled our country to overcome the narrow-minded machinations of former Prime Minister Steven Harper.  The limited life experience of neocons such as George Bush, Mike Harris and Steven Harper has been reflected in narrow-minded viewpoints which resulted in many disastrous policy decisions which detracted from the well-being of most people - other than a privileged few. These characters had very limited international travel experience prior to their election and none during their formative years.  "Bubble wrapped" thinkers indeed. 

When you walk around Granville Island, make sure to visit Longliner Seafoods Inc.  It offers some of the finest smoked salmon in the world - an exceptional gift to take back for the important people in your life.  (Yes, they will seal and bubble wrap your purchases for travel ... and you don't have to worry about refrigeration for the duration of your air travel home.  I can only imagine how the airport sniffer dogs might react when inspecting the baggage.)   


Sunday, 21 February 2016

New Series of Posts on Personal Health

This series will address a variety of topics on personal health - measures that one can take to improve one's ability to live an active life.

The first posts will be organized around physical well-being:
  • sleep (getting sufficient sleep and employing "creative dreaming" to get insights which are unencumbered by rational thought processes during wakeful hours)
  • movement (body mechanics) - this will be subdivided in several sub-topics: feet, balance, posture, preparation for physical activities such as skiing, golf
  • breathing
  • diet
  • exercise (here I'm talking about measures one can take to develop a constitution which is capable of sustaining prolonged activity as opposed to body building, one of the most useless approaches to a fully functional body.  
The posts will chronicle my journey:
  • the experience of relearning how to walk after encountering leg pain which laid me up for two days in Burgos while I was walking the Camino de Santiago de Compestella - also lessons learned in making plantar fasciitis a distant memory
  • exercise, posture and movement routines which laid to rest a diagnosis by a leading surgeon that I would suffer from debilitating back pain by the age of 40 (imagine getting this news at 16 years of age!)
  • learning how to use the power of sleep
  • dealing with joint problems without the aid of NSAIDS and surgery
  • learning how to listen to my body and to become more efficient when skiing, golfing etc. 
As opposed to being prescriptive, the posts will simply hint at a direction which might be explored by others.  As in the realm of investing, it always pays to check the credentials of informants and their motives for offering "advice" to consumers.

Sadly, the area of personal health is filled with ill-informed individuals/ideologues/charlatans, and snake oil salesmen whose advice/services/products can be dangerous to one's health.  The literature is replete with "born again" individuals who made dramatic changes to improve their physical well being.  Many of them have no room for the possibility that other regimes can lead to healthful results.

The medical community sometimes has very different viewpoints on various aspects of health.  It is not surprising:

  • many companies (e.g. footwear manufacturers) sponsor research which presents a favourable views on their products and services (always check to see if the research is peer-reviewed by reputable institutions)
  • sometimes, new research takes time to be accepted by a community which is, by nature, conservative in its outlook (for good reasons)
  • many studies are small in scale (size, time) and for this reason, do not have the "weight" to influence the wider community even though results might be useful
  • the politics of funding has a great influence on the direction of research.
In light of this, it is prudent to place more weight on peer-reviewed findings.  

However, I have found that the writings of people who have a long and successful history of treating endurance athletes are valuable. They share a variety of characteristics:
  • the authors have many years of treating high performance athletes
  • their "prescriptions" emphasize natural movement and function as opposed to drugs and equipment
  • they leave the gate open to interpretation and experimentation and place the onus on the individual decision as opposed to prescriptive dogma
One Final Observation

People are different.  They respond differently to diet, exercise and the demands of daily life.  It literally pays to bear this in mind while charting your path forward.  

You can start by watching this:


Whether you're running, swimming, cycling, or hula hooping, we have always been told that doing regular exercise will improve our bodies and is one of the keys to a healthy and happy life. Our one-size-fits-all approach to maintaining an active, healthy lifestyle is very rarely questioned, but with recent advances in genetic testing technology and brain stimulation techniques, scientists are uncovering the new and surprising truths about what exercise is really doing to our bodies, and why we all respond to it differently. In this programme, Michael Mosley uses himself as a human guinea pig to discover the truth about exercise

Thursday, 18 February 2016

Some Noteworthy Trends: Blockchain - a very significant development and The End of Moor's Law: the next frontier

Blockchain

http://www.wired.com/2016/02/ibm-and-microsoft-will-let-you-roll-your-own-blockchain/?mbid=nl_21716

You will hear a lot more about blockchain.  You can Google "blockchain" to learn more.

It is possible to invest in this technology.
http://www.investopedia.com/articles/investing/120315/5-ways-invest-blockchain-boom.asp

http://www.blockchaintechnologies.com/blockchain-investments

My search is just beginning ... a more detailed posting will be made in a few weeks or so.

The End of Moore's Law

An observation made by Intel co-founder Gordon Moore in 1965. He noticed that the number of transistors per square inch on integrated circuits had doubled every year since their invention. Moore's law predicts that this trend will continue into the foreseeable future.
http://www.investopedia.com/terms/m/mooreslaw.asp


However, it appears that the trend is slowing for two reasons.

Manufacturing costs have risen significantly (see next URL)

The beginning of the end started about a decade ago when the size of transistors – less than 90nm, or a hundredth of the width of a human hair – led to overheating. The problem was solved by limiting the speed of the processors, so they couldn’t generate too much heat. But the problems continued.

Transistors were set so close to each other that they were interfering with one another’s functions. They are now approaching a size so ridiculously small at 28nm or below, that they won’t follow the normal laws of physics such as gravity – they will soon be impacted by “quantum effects” which means their behaviour becomes unpredictable, and we can’t use them in nuclear power stations and rail networks.
http://www.telegraph.co.uk/technology/2016/02/25/end-of-moores-law-whats-next-could-be-more-exciting/?WT.mc_id=e_DM91975&WT.tsrc=email&etype=Edi_Cit_New_Tue_9Sections&utm_source=email&utm_medium=Edi_Cit_New_Tue_9Sections_2016_02_26&utm_campaign=DM91975

The above-noted article notes:

What we now need from our devices is better battery power, energy efficiency, better connectivity and design.

The new ‘More than Moore’ road map will need to work backwards – what devices and applications do people want, and how can the chips we make support them efficiently?

The technical aspects of the issue are fascinating.  Given the intellectual and financial resources currently being allocated to these pursuits, it is inevitable that some breathtaking advances advances will be made in the near future.  The advent of more efficient and compact batteries, for example, will revolutionize the power distribution grid, especially in areas of the world which are "under-serviced".

However, I believe that the most significant advances will be made in the conduct of human activity: social and economic innovation enabled by technological advances has the potential to change radically, the way we communicate and do business.  Blockchain is only the start.

Monday, 15 February 2016

Gold - An Investment Strategy

Gold has been dismissed by many as a relict of the past - an artifact of times when banking systems were not well developed and where there were few alternatives for people seeking security for their stashes during turbulent times.

In North America, especially, the literature is filled with such commentary.  It is there that people have never had the recent experience of war and other wealth destroying events such as famine, disease and other agents leading to social insecurity such as widespread corruption and the absence of the rule of law.

The simple fact is that the majority of the world's population holds a different view and regards gold as a store of value during hard times.  This view is starting also to take hold in North America.

Recent market instability has raised investors' interest in gold.  If you believe the supply/demand functions in the global market for gold (some people don't) this is reflected in the price of gold.

http://www.goldpriceoz.com/goldpricegraph/usd-gold-price-per-ounce-3-months-history.png

This increase has been reflected in the performance of the S&P TSE Gold Index


Gold-based equities in the Financial Log Book have performed nicely in recent months.

Company
Purchase Price/Date
Current Price
12/02/16
% Increase YTD
% Gain/Loss Since Purchase
Abitibi Royalties RZZ
2.57
2015-11-20
3.4
1.2
31.4
Silver Wheaton SLW
12.37
2007/09/04
21.15
23
71

Speculation in several other companies has been profitable.


Here is a list of companies on my radar screen.  It was developed as a result of looking for enterprises with characteristics noted later on in this commentary.

Asanko Gold
Franco Nevada
GoldQuest Mining
McEwan Mining
Premier Gold Mines
Pretium Resources
Oceana Gold
Integra Gold

The companies generally share the following characteristics:

  • great management with a good track record
  • operations in stable jurisdictions where the rule of law prevails
  • lower all-in sustaining costs 
  • good balance sheets and/or an ability to secure additional funding for development
I prefer companies with active operations and a income stream. Why?
  • technical/operating risks are lower with the result that additional funding can be secured at lower rates
  • in some instances, production can be ramped up relatively quickly to profit from higher prices during boom times
There are some exceptions to the above-noted generalities.  Asanko Gold is in a fairly stable African country but the upside potential warrants the additional risk of geopolitical uncertainty.  Pretium Resources is scheduled for production in 2017.  It is fully permitted and appears to have good access to funding.  Its main attraction is the size and quality of its high grade reserves and the prospect that they will be increased over time.

A host of other variables figure in my decisions:
  • The possibility of a take-over.  Some companies are likely take-over candidates.  Small to mid-sized companies with significant reserves sometimes fall within the sights of larger entities seeking to replenish their reserves with less risk than greenfield exploration activities.  In this respect, I look for small mines (preferably under development) which are adjacent to larger ones.  Sometimes the attraction of reducing costs through the sharing of processing facilities leads larger companies to absorb their smaller brethren.  This is interesting:How Are North American Gold Miners Placed?
  • I prefer companies which are located in established gold fields. The reasons: an established infrastructure which lowers costs, an established social fabric which facilitates regulatory approvals, community support and access to labour.
I like companies such as Franco-Nevada, a gold-focused royalty and streaming company.

Our business model is to grow the royalty portfolio with acquisitions of high quality, high margin assets limiting our downside exposure but retaining the full upside potential of higher commodity prices and/or new exploration discoveries.

The company has great management.  It is well worth viewing the most recent investor presentation: http://www.franco-nevada.com/wp-content/uploads/2016/02/Antapaccay-Precious-Metals-Stream.pdf

In these times when miners are desperate to secure financing, streaming/royalty companies are well-positioned to secure profitable contracts.

A position  in Franco Nevada was established on 2014-08-22. Since then, the price has increased by 23.9 percent (12/02/16).  I continue to hold this company.  The investor presentation outlines the company's interests - they warrant serious attention by investors seeking to invest in specific companies.

I have invested in most of the afore-mentioned companies from time to time and have taken profits as opposed to hanging on for more.  The only exception is with the royalty and streaming companies where I plan to hold on through what I sense will be a cyclical rebound in the precious metals market.  In essence my strategy involves:
  • short-term speculative ventures and profit taking based on my sense of the market action
  • longer-term investments in companies with proven revenue streams from a variety of mines located in stable jurisdictions
The result has almost negated the impact of declines in some holdings noted in the Financial Log Book.  

Note:  Other than generalized observations, I will not record this speculative activity in the Financial Log Book.  

Wednesday, 27 January 2016

Decline of the TSX Venture Exchange - discussion morphs into a review of the periodic table of investment returns

The following graphics were compiled by The Visual Capitalist. It's one of my favourite sites. 


Visual Capitalist TSC Venture Exchange from 1990 to Present

The massive decline in resource-based stocks, the life blood of the exchange, has disenchanted investors and other players.  This is typical:
http://business.financialpost.com/news/energy/revitalizing-the-tsx-venture-has-high-priority-in-2016-for-broken-exchange?__lsa=53fe-91ae

A Falling Tide Lowers All Boats ... the captains are hapless victims

Over the past 3 years, many resource-based funds, especially those focused on precious metals and oil and gas, have recorded tremendous losses.  Out of curiosity, I checked the credentials and performance records of the account managers who helm many of these funds.  Here are a few findings:

  • all of them were well educated with backgrounds in the areas of business, economics and engineering
  • all had the requisite professional certifications 
  • most had been in the business for more than a decade and most had recorded impressive portfolio performances during the height of the resources bubble
This notwithstanding, their performances in recent years have been dismal in real terms - the result of constraints imposed by the investment parameters of their funds.  It's almost as if they are locked on auto pilot, unable to change course in the face of the shoals ahead.  In other words, they have little option but to soldier on, go to cash, or close their funds.  

Fund managers have little choice but to be optimistic as it is not in their career interest to discourage bruised investors: 

The energy sector has been a challenging place for investors for several years now and many investors’ patience levels are being tested (to the extreme!). This has been the worst oil price correction in nearly 45 years and the pain inflicted has been significant. The greatest risk today is not in being invested in energy stocks but rather in buying into the fear of today, every time an economist tries to steal headlines with the lowest possible short-term prediction for the oil price (we are almost at the point where the next prediction will be for a negative oil price). ... The only thing missing now is a bit more patience and a few more months to get through the worst period of refining activity and the resumption of Iranian production. After that, investors should focus on inventory withdrawals and the rebalancing of the market. It is at that point when the price of oil should begin its recovery and oil stocks along with it. 

http://sprott.com/media/318873/sprott-energy-fund-monthly-commentary.pdf

Periodic Table of Investment Returns

The following table chronicles the rise and fall of investment tides in various sectors.

Periodic Table of Sector Returns 2006 to 2015

The periodic table has been used by many to extoll the virtues of diversification.

I take a different view.

  • Diversification for its own sake is fine if your goal is to achieve returns which approximate general market indices, in which case, your best option is to purchase various market index ETFs.  
  • There are some long-term trends which, in my opinion, favour certain sectors over others in terms of providing opportunities for financial gain.  For example, an aging population in wealthy countries will only increase the demand for products and services in health care.  Growing affluence and rapidly expanding populations in many parts of the world, coupled with the disruptions of climate change, have created ideal conditions for long-term investments in agriculture. Infrastructure is another theme: renewal and new build.  
  • Most important, the foundation of my portfolios is comprised of companies with excellent management, stellar balance sheets and competitive business models.  Diversification for its own sake is a non-starter.  

The following paper provides a concise and thoughtful overview of a sector-based approach to portfolio construction.

Equity Sectors: Essential Building Blocks for Portfolio Construction

The takeaways:
  • Applying a sector-based framework to equity portfolio construction can help investors achieve a variety of alpha-seeking investment objectives and greater control in managing portfolio risk.
  • Beyond company-specific factors, sector exposure has been the most influential driver of equity market returns, yet sector-based portfolio construction remains an under-utilized strategy in the marketplace.
  • Equity sectors have a variety of attributes, including stable classification, consistent earnings drivers, high return differentiation, clear volatility patterns, and low correlations, which together can help investors generate efficient portfolios
  • Sectors can be used as portfolio construction building blocks through a variety of investment strategies, including sector allocation, portfolio overlays, portfolio completion, and risk management, as well as to diversify wealth beyond human capital exposures.
When starting out in investing, I got caught up in the intricacies of trying to navigate my way through various investment strategies.  It was unproductive.  After several years, I concluded that most of the strategies were developed primarily by academics as opposed to people who put their own money on the line.  I also learned that modelling supported by back-testing tended to produce investment strategies which generated an attitude of over-confidence on the part of their practitioners .... sometimes with disastrous results when the realties of life trumped theoretical models.  A classic example is Long-Term Capital Management.

I have watched the rise and demise of many investment strategies and concluded that the following approach suits my temperament:

  • emphasis on sectors with the potential to generate substantial gains over the long-term
  • periodic speculative investments in small companies with products/services with the potential for significant gains
  • and always, a focus on companies with excellent management, great balance sheets and a competitive position 
It is very much an "active" approach - one which demands constant learning and forays into unfamiliar ground, especially when investing in small innovative companies.  It also entails a mindset able to sustain heart-stopping losses when the market sentiment of the moment is negative e.g. fear has driven down prices in sectors such as agriculture, seemingly ignoring some very compelling long-term considerations which favour future prospects for financial gain.  

This approach is not suitable for everyone, nor should it be.  As my father-in-law used to say, "That's why they make Fords and Chevs."


Wednesday, 13 January 2016

Oil and the Middle East

Much has been written about Saudi Arabia's efforts to capture a larger share of the global oil market.  The common view is captured in the following sentences:

Why did the country opt not to cut production? Saudi Arabia is one of the main players in the oil market, supplying 12-13 percent of the total daily oil output worldwide. As the second biggest oil producer after the US, it wants to preserve its share in the market and a cut in production would threaten this share, which takes a long time to regain.
http://www.investopedia.com/articles/investing/031715/how-saudi-arabia-benefits-low-oil-prices.asp

However, things are not that simple, even if the above-noted thesis is taken at face value.  Things change.

Saudi Arabia's reputation in global affairs, while never stellar, has suffered recently and attitudes between it and many countries have changed:
  • technological advances in oil and gas exploration and extraction have reduced the commanding position once occupied by Saudi Arabia in the global supply of oil and gas - other areas have increased production and other non-fossil energy sources are becoming more viable
  • concurrent with a reduced reliance on Saudi oil is a developing global impatience with Saudi Arabia's export of Wahhabism and the disruption it has caused within and outside the Islamic world - the country is becoming more isolated diplomatically
  • the negotiation of the Joint Comprehensive Plan of Action to (JCPOA) concerning Iran's nuclear program has had two major consequences for Saudi Arabia: the release of Iran's frozen financial assets and more importantly, increased access to foreign markets for its oil.  The agreement was negotiated in the face of strenuous opposition from Saudi Arabia
At the same time, Saudi Arabia must contend with a very young, underemployed and potentially volatile population.  At present, social peace has been purchased in the form of all manner of subsidies for housing, fuel and social support programs.  The social fabric is under strain and could rupture suddenly. This is complicated further by intense jockeying for power amongst the ruling class, an outcome which could result in further uncertainty. 

While oil markets are depressed, the potential for conflict in the Middle East between Saudi Arabia and Iran is greater than in years previous.  

Here is a very interesting take on the relationship between Saudi Arabia and Iran, one of the best I have read in years.  As always, it is worth noting the credentials of the author.  

Sinking oil prices (crude dipped below $32 this week) further diminish the costs for risky behavior and mute international repercussions. Iran, for one, would be relieved to see Gulf tensions raise oil prices as it tries to reenter the global energy market.
Saudi leaders are determined to forge political order within and outside its borders. Its actions and rhetoric this week show that they cannot do so without resorting to sectarianism and bellicosity. As Saudi Arabia’s marginal returns of confrontational policy diminish due to unfavorable circumstances in the Middle East and inside the Kingdom, it must increasingly ratchet up the stakes to retain the same level of return and benefit. However, violent sectarianism is not a manageable policy, and can empower forces—such as ISIS—that will be further detrimental to regional order and to the stability of Saudi Arabia itself.
A New Era of Brinkmanship in the Middle East

Most important, I believe that the ruling class in Saudi Arabia is isolated from the realities of life in the kingdom.  It has the luxury of unprecedented wealth and is not accountable to anyone except a limited constituency (the clergy, military).  This isolation, whether intentional or an unintended by-product, has the potential to re-enforce prevailing attitudes and adherence to established ways of conducting the business of government.  There are few avenues for gradual change (e.g. meaningful elections, more equitable ways for citizens to participate in the economy).  As a result, change often takes the form of revolts ... small surprises have the potential to ignite major shifts as per the Arab Spring ... the clock is ticking.

I have compiled a list of oil and gas companies which could increase production quickly in the event of a disruption (or the hint of a disruption) in the flow of oil from the Gulf.

Some characteristics:
  • cash on hand and access to sources of additional money
  • operations in stable countries served by the rule of law and a robust infrastructure to support the industry
  • production which could be brought on stream very quickly at low risk
  • a record of low costs achieved through efficiencies which will add to profitability
  • ownership of processing facilities and ready access to pipelines and/or rail transportation
  • excellent management
Contingency planning perhaps, but for all of his faults, Baden Powell had it right:


Monday, 4 January 2016

Ligand Pharmaceuticals (LGND) - To Anchor or Not to Anchor

I have yet to make a decision on this stock. Why?

  • the company's presentation is compelling
  • its business model has potential
  • management has rewarded itself at the expense of share owners
  • its primary revenue streams are not ironclad 
  • I suspect that its stock price has risen on a tide of optimism in the biotech/pharma sector

My voyage started with a survey of pharmaceutical companies. The search broadened as a result of insights gained from two references which are cited below under Overview.

Some key points emerged during the initial phase of my reading:
  • the sense that information management (Health Care Big Data) will be one of the dominant drivers shaping the future of health care delivery e.g. the development of drugs, delivery of health care, evaluation and pricing of services 
  • the forces of transformation will eventually force the conservative culture of the medical community and pharma industry to change
  • dominant players (payers, information managers etc.) have shown an ability to adapt; they appear to have an advantage as a result of their size and access to data; and, they are adopting a variety of different strategies which provide informed investors with considerable scope to make judgements on the relative effectiveness of company strategies
  • markets for goods and services differ considerably across the world depending on patterns of disease, population genetics, ability to pay, population structure, culture, and so on
  • there is a role for specialized niche players
The Pharmaceutical Industry - Overview

Here are a few useful references which I would urge everyone to read:

Pharma and Biotech Industry Outlook
I came across this while searching on Google images.  I clicked on a graph in images and found a very interesting web site named Slide Share.  Founded in 2006 with the goal of making knowledge sharing easy, Slideshare joined the LinkedIn family in 2012 and has since grown into a top destination for professional content. With over 18 million uploads in 40 content categories, it is today one of the top 100 most-visited websites in the world.
I have subscribed to the site - some great reading.

The above-noted reference provides an overview of the industry: the players, trends, implications for the future.

From Vision to Decision - Pharma 2020
A comprehensive overview including tailwinds and headwinds - check out the meaning of "HONDAs" -  individuals who account for 70 percent of healthcare costs.  Don't be one of them.

The document provides a useful synopsis of the decision-making processes of pharma companies - something which is vital if you are planning to analyze the prospects of a potential investment.  I was especially interested in the range of strategies for drug development.  Fascinating.

The above-noted papers are two in a series of five: http://www.pwc.com/gx/en/industries/pharmaceuticals-life-sciences/pharma-2020/business-models.html

Can Big Data Fix Health Care?
This is a well written article, replete with a variety of embedded references of high quality.  It makes a compelling case for the likelihood that big data will be the vehicle to transform our health care systems.  For one thing, the current models will be unaffordable in much of the western world due to an aging demographic and competing demands for government funding. Doctors and other conservative elements will be forced to change when confronted with the realities of evidence-based policies on the part of those who fund the medical system.  There will be considerable friction in the competition for control, but it need not be a win/lose situation for participants.  This reading has fundamentally changed the way I look at the health care system.

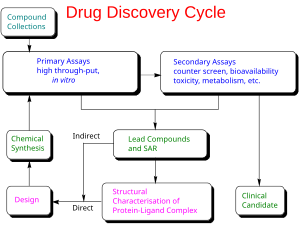
The Drug Discovery and Development Cycle

There are two basic aspects to bringing a new drug to the market: discovery and, development.

A.   Discovery


A description of the discovery cycle is presented here:
https://en.wikipedia.org/wiki/Drug_development

The advance of genomics and greatly enhanced capabilities of managing "big data" has revolutionized the cycle - increased its speed, increased the potential to "target" drugs more effectively in consideration of genetic variation in recipient populations, and in refining the composition of candidate drugs.

B.  Development


This part of the cycle is lengthy and entails tremendous expenditures and risks on the part of drug companies - in excess of $1 billion per drug if everything goes "right" and there are no bumps along the road.  There are many potential points of failure on the way to the market place, including: toxicity, failure to deliver anticipated results, unwillingness of government to pay, and a reduction in anticipated revenues through government demands for cost effectiveness studies, etc.  Even after drugs have reached the market, companies always have to consider the prospect of competition from cheaper, more effective remedies.

In 2014, an article was published in Nature analyzing the clinical development success rates for investigational drugs. It's no surprise that the success rates are still somewhat dismal with 1 in 10 drugs that enter clinical phases pushing through to FDA approval. The article breaks down the success rate in each phase for differing classes of drugs as well as various therapeutic indications. NMEs were found to have the lowest success rates in every phase of development (7.5%) whereas biologics had nearly two times the success rate (14.6%).
http://www.mdbiosciences.com/blog/drug-discovery-success-rates-the-role-of-preclinical-study-design

I will not pursue this in more detail in this posting.  However, there are some useful waypoints for investors:
  • the days of "blockbuster" drugs appear to be waning - some tremendous profits are being made with drugs such as Crestor but many cash cow blockbuster drugs are coming off patent, meaning that cheaper generic drugs will erode profits of the original developers
  • large pharma companies are adopting a variety of different corporate strategies for discovery and development (see first two references for more detail) without any guarantee that they will be successful as in the days of olde
  • there is a trend for custom drugs targeted to specific (sometimes rare) diseases and the genetic make-up of individuals and populations but with lower returns to a company's bottom line
  • the role of information is increasing in importance both in formulating compounds and in testing them more effectively
  • government is more amenable to changing the approval process to both shorten and make approvals more effective, including monitoring drugs once they have entered the market
  • collaboration between countries in the approval and monitoring process appears to be increasing
  • some drugs claim to double life expectancies but in the case of terminal diseases how can the public be expected to pay tremendous sums when lives are extended only by 18 months or so at a cost in excess of $50K  per individual (not including associated medical costs)?  I suspect that medical funding could be allocated for more robust returns.  It will be very interesting to follow Canada's policy for assisted death as it appears to be signalling a sea change in public attitude.   
The larger multinational pharmaceutical companies have operations which encompass discovery and development.  They are complex, difficult to understand,  and  companies are challenged with the need to adapt to rapid advances in technology (including information management), the changing nature of the health delivery system, and cash-strapped governments which are insisting on a greater measure of "value".

In light of this, I decided to focus on smaller entities specializing in drug discovery where investments are comparably smaller than in drug development.  In essence, beasts of this nature are more "knowable".

When investigating companies in the discovery niche, I looked for beasts with the following characteristics:

  • excellent management with a long history of working in the area of discovery
  • technical excellence and services/products with a competitive advantage
  • the ability to partner effectively with larger entities
  • a business model which reduces risk by concentrating on the company's expertise
  • the potential for significant gains as a result of contractual arrangements with clients

Ligand Pharmaceuticals (LGND)

As a result of reading the aforementioned sources and leads which emerged in the course of that reading, I started to focus my attention on a few companies.  I narrowed my search to LGND, a niche player which is involved in early stage drug development.

Why?
  • Its business is focussed and comprehensible.  
  • Its business model appears to be a good fit with the modern pharma business. 
  • It has demonstrated an ability to change its business model to exploit opportunities
  • A few larger participants in the systems require a "jump of faith" for investors as the businesses are complex, prone to major disruption as a result of government intervention, potential legal difficulties, and competition.  
The share price has increased by more than 1000 percent in the last five years.  Normally one would be cautious in making an investment on the basis of this performance as most companies are unable to create value of this nature over a prolonged period.

However, as I started to investigate the company in more detail, my research started to focus on a few aspects related to the nature of the pharmaceutical industry (competition, government regulation and approval process, future demand) and the strategic position of Ligand Pharmaceuticals.  Once this was done, I concluded my research with an investigation of a few areas specific to LGND: management, balance sheet, income streams etc.

Here is a very informative 127 page investor presentation.
http://content.equisolve.net/_d41d8cd98f00b204e9800998ecf8427e/ligand/db/184/592/pdf/Analyst+Day+Nov_18_2015v+Full+FINAL.pdf

Read it diligently and you will develop a good understanding of the company's strategic positioning, its business model and its operations.

Ligand is a turnaround story: activist investor seeks to extract value - turnaround expert stays around ...
life-after-loeb-ligand-pharmaceuticals-prospers-in-stripped-down-mode/

john-higgins-of-ligand-pharmaceuticals-on-restructuring-a-business-and-streamlining-operations-how-to-refocus-your-business-by-setting-priorities/?all=1

I was almost ready to purchase shares, but as always, I dream about a potential investment for a few nights (creative dreaming).  I wondered about the company's profitability over the long term. Sometimes, you can cut too much by way of monetizing assets. I've learned that many of most profitable advances come about as a result of chance conversations and curiosity.  Some companies are more able than others to create this environment.  It is not something that can be measured on a balance sheet.  I don't know if LGND has the critical mass of people to do this, especially when main office is concerned primarily with managing relationships. Also, it's a real management challenge to cultivate this climate when participants in an enterprise are separated by distance and organizational units.  This is the "softer side" of evaluation.  I've seen several companies which have this "magic jelly" and I'm not convinced that I see it with Ligand.  I may be wrong and will leave it to readers to arrive at their own conclusions.

In the light of day, I started looking for potential shoals:


Sometimes, when entering a particularly challenging anchorage which is new to me, I will drop the hook on the approach and then take to the dinghy to explore the situation in more depth (pardon the pun).  Only when I am satisfied that there is a good margin for safety will I make a decision to proceed.  I follow much the same procedure for investing.


Friday, 1 January 2016

Financial Passage Maker - Performance January 2016


Entity
Initial Price/ Purchase * Date
Price *
Dec 29/15
Gain/Loss
since Jan 1/15
%
Gain/Loss
Since Purchase
%
Silver Wheaton
(SLW)
12.37
2007-09-04
17.07
-26.8
38
Polaris Materials Corporation (PLS)
10.70 **
2007-06-01
1.57
-9.7
-85.3
Cenovus (CVE)
32.39
2010-07-27
17.41
-24.9
-46.2
North West Company (NWF)
16.23
2009-05-07
28.86
15
77.8
Deere & Company (DE)
88.07
2013-01-03
77.5
-9.8
-12
Rocky Mountain Dealerships (RME)
11.89
2013-01-03
6.16
-29.7
-48.2
HollyFrontier (HFC)
47.95
2013-01-28
39.81
9.8
-16.9
Oak Tree Capital Group (OAK)
56.45
2013-10-28
48.19
-4.9
-14.6
Fairfax Financial Holdings (FFH)
477.98
2014-3-25
661.97
11
38.5
Clean Seed Capital (CSX)
.51
2015-01-07
0.65

27.5
Abitibi Royalties (RZZ)
2.57
2015-11-20
3.49

34.9
Input Capital (INP)
1.86
2015-11-20
1.76

-5.4
Marquee Energy (MQL)
.49
2015-11-23
0.41

-17.3
Fairfax India Holdings Corp (FFI)
10.42
2015-12-16
10.05

-2.3
CRH Medical Corp (CRH)
4.43
2105-12-29
4.29

-3.2


*    Prices are quoted in the currency of the exchanges where equities are listed.  As a result the gain/loss is not an accurate measure of the performance of the portfolio as the   $US has risen significantly against the $=Cdn since many US positions were established.  
** does not reflect impact of a large follow-on investment @ $.67 per share

Selected Commentary

Agriculture

The following quote says it all:

There is no point in mincing words: a recession in the farm belt is not "coming," "threatening" or even "likely:" it has definitely arrived. The only uncertainties about it are how deep it will be, how long it will last and how extensive the damage to the nation's agricultural base will be. It will not be the same as the late 1970's to early 1980's recession ─ it is not largely due to insupportable debt burdens. Rather, it is a consequence of excessive production meeting a barrier to the exports that would normally provide an escape valve for inventories.
http://seekingalpha.com/article/3750616-u-s-agriculture-in-recession-risking-depression

I was impressed by John Abbink's writing, so I looked for more and found this take on Deere (DE).  It makes a lot of sense to me.  I am maintaining my position: it is a good company; the dividends will still roll in; there is a likelihood that the company will use a decline in share prices for a share buy-back; and most important, the company is well managed and has been through bad times before. Besides, my time horizon on this holding is ten years and more.
http://seekingalpha.com/article/3717386-fiscal-2016-outlook-for-deere-and-co

It should be noted that all of the agricultural holdings in the portfolio have seasoned management who have been through low periods in the agricultural cycle.  The companies will survive through the “boom” and “bust” environment which characterizes this economic sector.  If anything, low prices represent a buying opportunity, something I have exercised with Rocky Mountain.  I doubled the number of shares in my holding.  The metrics look good and the dividend is healthy and not threatened.

I consider that Input Capital will the one holding to be less affected by low prices by virtue of its business model; however, the loss of three contracts has temporarily (in my opinion) depressed the price of its stock.  It is well worth taking this news in perspective:
http://s1.q4cdn.com/784243260/files/doc_news/Input-Capital-Corp-provides-update-on-streaming-contracts.pdf


The Oil Patch

I have compiled a short list of potential acquisitions and put them on a watch list.  The current situation of low prices will not last forever.  I've placed a special emphasis on selecting companies with with good balance sheets and the ability to ramp up production quickly.  Most important, I look for excellent management with a history of operating efficiently for several years on company holdings.  Lean times have left the survivors with the ability to earn outsized profits when oil prices recover ... and they will ... it's not different this time.  The watch list will be presented in a future edition of The Financial Passage Maker.

Precious Metals

Silver Wheaton was one of the first metals streaming companies.  I invested heavily in the company a few months after its entry into the market.  It was a spectacular investment for two reasons: its new business model gave it a jump on other financing models for mine development with the result that it secured some tremendous deals (mines had access to capital when it was most needed in return for selling a share in future production); and, gold and silver prices rocketed upward thereby enhancing the value of SLW's metal streaming agreements.  It was only a matter of time before competitors with similar business models arrived on the scene e.g. Franco-Nevada.  The following article provides a nice synopsis of Silver Wheaton's approach.
http://www.forbes.com/sites/greatspeculations/2014/10/01/a-look-at-silver-wheatons-streaming-agreement-for-the-constancia-mine/
Make sure to click on this URL which is embedded in the above-cited article.
https://www.trefis.com/stock/SLW/model/trefis?easyAccessToken=PROVIDER_7dd7a29579af2a79a590e35d77c19c0123af74c3

In today's environment of depressed metals prices, miners are looking for financing.  Some (which I tend to avoid) will issue additional shares thereby diluting the pokes of existing share owners ... Polaris Materials, come on down.  Others will negotiate traditional metals streaming agreements with the knowledge that there is some room to negotiate given that there are more competitors on the scene.

This said, I have noted a few trends in recent years.  One is that the terms of some streaming agreements allow mining companies to buy their way out of metals streaming contracts. Pretivm Resources, a company on my watch list, is a beast of this species. Second, private equity is stepping up to the plate more often. Generally speaking, investors of this ilk have the “long view” and are prepared to wait longer to learn the fate of their investments than publicly listed companies.

Streaming is starting to be the stuff of the financial press.  See the following example.
http://business.financialpost.com/news/mining/the-dark-side-of-metal-streaming-deals-strapped-mining-companies-trade-future-value-for-cash

I don't think that I will add to my positions in Silver Wheaton and Franco-Nevada.  If/when metals prices increase, the share prices will increase nicely.  However, there are some issues:

  • increased competition from other lenders
  • the shadow of a very large tax bill for SLW if the CRA is successful in pushing its case forward (likely as not, a deal will be cut to reduce the $US 567 million subject to taxation for the years 2005 to 2010)

Due to the cost of negotiating streaming deals, Silver Wheaton is largely confined to major deals with long-life mines.  Most often, these take the form of taking precious metal streams which are ancilliary to the main focus of large base metals mines ... but not always.  I believe that the mid-tier mines will increasingly resort to private equity deals with more flexibility e.g. the possibility of shorter streaming agreements with buy-back provisions.  While investigating mine financing, I became very interested in the other end of the scale – what I term the “micro financing sector”.

Abitibi Royalties is focussed on this sector and has done very well in recent weeks.  I wrote about it in a previous edition of The Financial Passage Maker.   The company is nimble and positioned to respond quickly to requests for small amounts of cash to maintain mining claims fees in return for net smelter royalties in the event that the claim is mined.  The company's strategy is based on the expectation/hope that it will get lucky with financing a successful claim.  In making its bets, however, the company is very mindful of the adage “the best place to find a mine is in the shadow of an old mine.”  Check this:
http://abitibiroyalties.com/theroyaltysearch/

Here is a recent interview with Ian Ball.  Note the following:

  • the fact that Ball is purchasing shares in his company in the open market
  • the possibility that companies might pool resources to buy mining royalties (generally mining companies stick to their own knitting – this may mark a significant development in the business)

http://www.bnn.ca/Video/player.aspx?vid=776614

My Investing Strategy for Precious Metals ... at the current time

My investing strategy entails:

  • maintaining holdings in metals streaming companies (Silver Wheaton, Franco-Nevada) with an intermediate to long-term view in mind i.e. the expectation that prices will eventually increase; and,
  • engaging in short-term speculation in gold and silver mining companies (see previous edition for selection criteria) and taking profits once gains exceed 20 percent or so (depends on my gut feel).  I've learned not to get greedy as the price of gold has been somewhat “choppy” in recent years, thus offering the potential for small, short-term gains (or losses).  And as always, I look for a catalyst with the potential to excite investor interest e.g. the beginning of full-scale operations at Asanko or significant new discoveries at Pretivm.  


It's amazing how the results of “base hits” add up over time. And I yet have the potential for some home runs if I get lucky.  And no, I am definitely not a “gold bug” - simply a person who has profited very nicely in the past and who sees a heightened potential for the cycle to repeat itself.

Investors would be well advised to look at the career of Rob McEwen.
http://www.theglobeandmail.com/report-on-business/careers/careers-leadership/rob-mcewen-mining-magnate-with-a-vision/article546293/?page=all

Investors appreciate his ability to promote his projects, manage cash wisely, and operate in the interest of share owners.  In mining ventures, it's all about management: 1st, 2nd and 3rd ... the mineral resource comes 4th.  I've learned to be assiduous in checking the pedigrees of mine management and boards of directors as a result.

Check my findings respecting the management of Arotech, a company which is in the cross-hairs of an activist investor who is seeking to shake things up in an effort to realize the true value of the enterprise.  (Write-up is presented the posting, Arotech - Some Thoughts to Consider When Making an Investment. )

Resource Stocks – When to Invest -  Some Interesting Links

http://www.mineweb.com/news/mining-finance-and-investment/mining-stocks-are-becoming-irrelevant/?v=3e8d115eb4b3

http://www.telegraph.co.uk/finance/markets/ftse100/12039422/Miners-in-meltdown-Mining-stocks-plunge-to-11-year-lows.html?

WT.mc_id=e_DM69465&WT.tsrc=email&etype=Edi_Cit_New_Tue_9Sections&utm_source=email&utm_medium=Edi_Cit_New_Tue_9Sections_2015_12_09&utm_campaign=DM69465

http://www.telegraph.co.uk/finance/economics/12040314/Fear-grips-market-as-oil-leads-commodity-crash.html?

WT.mc_id=e_DM69465&WT.tsrc=email&etype=Edi_Cit_New_Tue_9Sections&utm_source=email&utm_medium=Edi_Cit_New_Tue_9Sections_2015_12_09&utm_campaign=DM69465