Friday, 17 March 2017

The Landmark Trust - Wonderful Accommodation in Great Britain

I am planning a trip to England and Scotland.  As always, I look for accommodation which "interesting" - places which are destinations in their own right.  There are some appealing places offered by The National Trust and English Heritage, historical conservation organizations which have done wonderful work in protecting and interpreting England's heritage.  Their rental accommodation is well worth investigating.

Fortunately, I hit another mother load, The Landmark Trust.

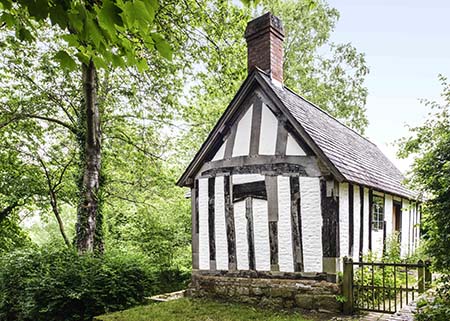
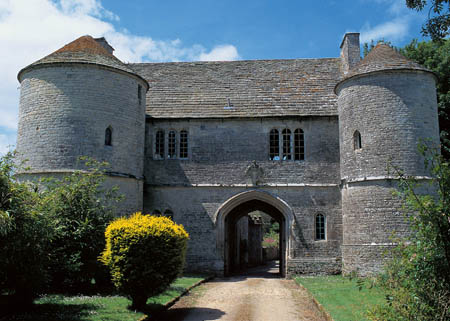
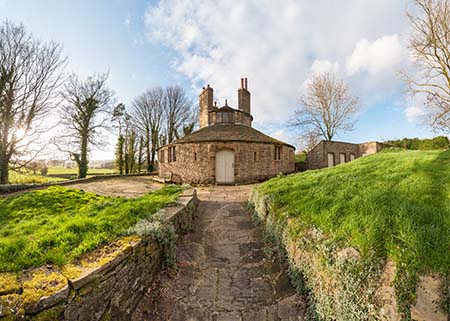
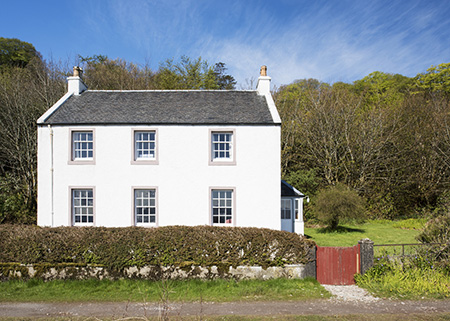
Briefly, the Trust restores noteworthy historic buildings and then rents them out to pay the freight.  It's a wonderful idea ... and the places are eclectic: everything from follies, to small castles, to modest fishermen's cottages.  Not often do you get the opportunity to stay in a medieval house ... or a castle ... or even where John Fowles lived in Cornwall for many years! Belmont House

As a concession to modern expectations, the restorations have conveniences such as effective heating, interior bathrooms and cooking facilities. Generally speaking, you will have the entire building to yourselves.  Some of the buildings accommodate two persons whereas others can sleep twelve or more. You can rent the premises for periods of the following duration: three or four days or weekly. Due to the popularity of the properties, it is advisable to make reservations well in advance.

We will be staying in four of the Landmark Trust properties on our next visit to England.  I'll describe them in a future post.

Here are a few examples of places on tap:  I've included an exterior and interior shot of each building.


Scale and Scalability - dimensions for evaluating potential investments


As one trained in geography, biology and the fine arts, I look at potential investments from a viewpoint which often differs from analysts who received their training in business schools.  In this post, I would like to address a few aspects of "scale" and "scalability".  The concepts are fairly simple on the surface.  In later posts I may expand upon some of the following basic concepts and also, expand the discussion to include more dimensions of "scale".

Impact

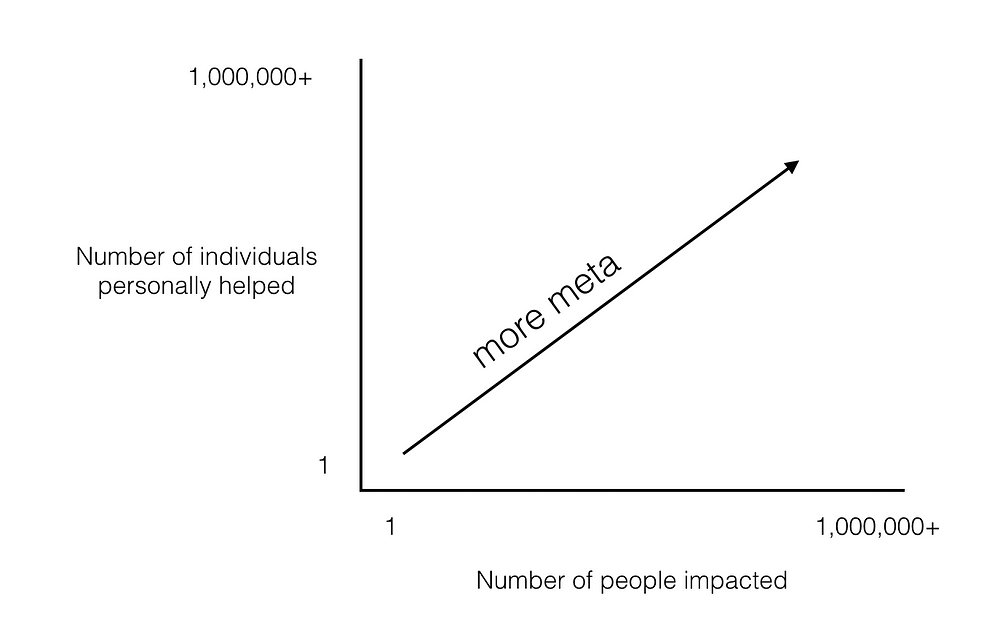
The following diagram was advanced by an entrepreneur who screens potential ideas by their potential to make a difference.  It is elegant.


The products and services of great enterprises have a global impact.  Tremendous profits can be achieved by investing in these beasts in their early stages i.e. Google, Microsoft.  It is extremely difficult to identify these opportunities, especially as the companies often have far-out, ground-breaking concepts which are unappreciated in the early going e.g. distribution models used by Fedex, marketing and distribution by Amazon etc.  

This is a tremendously powerful idea.  When searching for investment ideas, it often pays to push away from the table and think at a very high level.  This process often takes years; however, the "view" that emerges from such thinking can be extremely powerful.  Hint: don't look to think tanks and the bleatings of "futurists".  Look to the artistic community and outliers in society as these elements are often extremely sensitive to changes in the human condition.  

Scalability

Thank Heaven for Wikipedia!  Here is a very succinct overview of "scalability". 

Scalability can be measured in various dimensions, such as:

Administrative scalability: The ability for an increasing number of organizations or users to easily share a single distributed system.

Functional scalability: The ability to enhance the system by adding new functionality at minimal effort.

Geographic scalability: The ability to maintain performance, usefulness, or usability regardless of expansion from concentration in a local area to a more distributed geographic pattern.

Load scalability: The ability for a distributed system to easily expand and contract its resource pool to accommodate heavier or lighter loads or number of inputs. Alternatively, the ease with which a system or component can be modified, added, or removed, to accommodate changing load.

Generation scalability refers to the ability of a system to scale up by using new generations of components. Thereby, heterogeneous scalability is the ability to use the components from different vendors.[4]

Note:  I will add to this article over the next few days.  It is my first post that is published on the fly - an experiment.  

Thursday, 16 March 2017

Habits of Millionaires ... and an important footnote

I've read a great deal about wealth management and have tried to incorporate key gleanings from that reading into my approach to life.

Of course, the key to a "successful" life entails far more than having a fat purse ... but it certainly helps to have the wherewithal to pursue a "rich life".

Here is a cogent summary of the habits of wealthy people who have accumulated wealth through their own efforts:

The Top 10 Habits of Millionaires

There is a common thread to many of the habits; namely, "to invest in one's self". It's perhaps the single most important thing a person can do.

The Importance of Learning How to Invest

In our early years, my wife and I lived off one salary - the other one was banked. Our salaries were modest, but we reached the point where we were able to put 50 percent down on the purchase of our first (and only) house.  We paid it off a little more than 3 years later.

Our biggest mistake thereafter, I call it the "lost decade and a half", was not to invest our savings in a meaningful way.  Instead, I relied on others and parked most of our grubstake in mutual funds.  Further, we lessened our savings rate.

Then, things changed significantly: a new government came in and implemented massive cuts to the civil service where I worked.  I had the misery of giving notice to 35 percent of my staff.  There was no assurance that I would not be next as the axe continued to fall.

I resolved from that point forward to gain a measure of financial independence: to be in a position to have the resources to retrain and start a business of my own in the event of a firing.  From 2:00 to 4:00 AM every day, I worked on learning how to invest.  After 8 years, I was making more from that than from my wages - this despite several promotions.

At first, I hated the activity, but soon I became captivated by the thrill of learning new things, the psychology of investing, and the "hunt" for potential investments.

In so-called "retirement" from the wage economy, I still find great satisfaction in investing activity.  Further, it has enabled us to pursue many new interests and to assist family members in starting new businesses.

One of the best things you can do for your kids is to give them a strong set of values to live by.  Helicopter parenting is an anathema: more than ever, kids will require resilience and a strong sense of self in order to cope with a world which is changing rapidly.  And I would argue that the skill sets and approaches which sustained parents through their early years may be insufficient to meet the challenges of the "new world".

This said, values are enduring - it's just that kids will have work out how they are expressed for themselves.

One of the key values is embedding in one's kids, the approach of being successful financially, hence this post.
Evaluating Mine Development - A Short Post

I have written previously about investing in mines, primarily those focused on gold and silver.

My criteria are fairly simple:

  • the quality of management is key
  • stable geo/political jurisdictions - I never stray 
  • located in areas with good supporting infrastructure (financial, logistical, personnel)
  • strong balance sheets 
  • preference for working mines or those which can be "de-mothballed" fairly quickly
  • the prospect of markets which make operations profitable

It's always useful to review one's approach and refine it as appropriate.  Here's another group of considerations.  I'll not steal the punchline: the article is short.

Getting Big Mining Projects Right

Wednesday, 8 March 2017

Clean Seed Capital - starting to sprout

I have written a few posts about this start-up company.

Briefly, CSX has developed the CX-6 Smart Seeder.

The SMART Seeder™ offers an unrivaled level of precision in modern no-till seeding. This drill demonstrates the future of farming.

Clean Seed has developed an advanced precision no-till seeding system comprising several individually patented technologies, including in-ground openers, proprietary seed and fertilizer metering, and electronic control systems. Our most recent ground breaking achievement is also our most advanced and innovative to date: the award winning CX-6 SMART Seeder™, which is an industry first!

It represents a major advance in seeding technology for large scale farming operations:

  • can plant seeds at variable rates very precisely in order to fulfill the requirements of precision agriculture
  • has the capacity to deliver other products (e.g. fertilizer, pesticides) simultaneously and at variable rates
  • it enables farmers to practice intercropping to increase yields and profits http://us7.campaign-archive1.com/?u=07f7d9dee595a47b1c531c8f4&id=dc42a7d073&e=6ffb8de420
  • has a modular system whereby malfunctioning parts can be replaced quickly in the field

More detail is provided here. 

http://www.cleanseedcapital.com/home

I was privy to a confidential report on field tests of the prototype and it was superior to anything on the market.  (I obtained this by writing to the President to learn more about the technology - this when I was evaluating a potential purchase of stock.)  Since that time, the SMART Seeder has undergone additional field testing in a variety of conditions/geographies.

In recent years, the company has developed a production capacity by means of an agreement with a respected equipment manufacturer and has also entered into distribution agreement with Rocky MountainEquipment, a company which I established a position with several years ago.
https://www.rockymtn.com/

Recently, Clean Seed made the following announcement:

February 23, 2017 - Vancouver, British Columbia - Clean Seed Capital Group Ltd. (“Clean Seed” or the “Company”) (TSX-V: CSX) has entered into a distribution partnership agreement with Torgerson’s LLC (“Togerson’s”) to bring its CX-6 SMART Seeder™ technology to the United States through 1) an exclusive dealership arrangement for Montana and North West Dakota 2) the creation of a CX-6 SMART Seeder™ demonstration centre and 3) providing a base for further expansion into other key US markets.
http://www.cleanseedcapital.com/blog/post/clean-seed-capital-group-tsxv-csx-enters-the-united-states-market-through-new-strategic-alliance-and-closure-of-associated-investment-1

I have great expectations for Clean Seed:

  • It has been able to secure financial support at all times and has no debt.  
  • It has progressed in a very deliberate way, building its technology and the supporting infrastructure to bring its product to the marketplace. 
  • Management is communicative: I received a response from the the President within hours of writing him by e-mail.  The response was fulsome and direct.  
  • Clean Seed's team has "mud on its boots" and strong links with the farming community.  
  • It appears from recent additions to its Board, that the company is clearly positioning itself for expansion into additional markets. 
The investment has required patience and a recognition that the path to success has many twists and turns:
  • It is common for stock prices in new ventures  to gyrate significantly (and it certainly has)
  • New ventures require agility: a willingness to bring new people on board to build management capacity as the technology develops and to bring it to the marketplace  (Clean Seed has done this in spades)
  • Many technologies fail because they do not bring quantifiable benefits to customers.  It would appear that the field trials have demonstrated this effectively.  Farmers tend to be "show me" people and are loath to accept the blandishments of slick "suits".  
Here is a synopsis of four keystones for the success of agricultural start-ups.  It would appear that Clean Seed has the "right stuff":

This said, there are a few issues with the potential affect the fortunes of this company:
  • Trump trade policies
  • the state of the agricultural cycle (my sense is that we are near/at the bottom of the cycle and that things will improve over the next several years)
  • manufacturing glitches and the inevitable issues in the field which arise with the advent of new technologies (operator error, equipment deficiencies)
  • competition: Clean Seed is a new entity and must compete with well-established companies with deep pockets and long-standing customer relationships.  
  • in the short term, it is getting more difficult for farmers in the Mid-West and elsewhere to secure financing for equipment purchases given a regime of low prices for crops such as corn and soybeans https://www.farm-equipment.com/articles/13760-deu
To my mind, there are two potential scenarios regarding the future of Clean Seed:
  1. Organic growth: a slow process whereby the company grows its market and adds other products over time.  
  2. Take-over by a larger corporate entity.  Case IH comes to mind as its product line is carried by Rocky Mountain et al.  
My bet is on the second scenario, although I would prefer to watch Clean Seed develop to the point where it could command a higher price point.  

I have steadily added to my position over time as the company has passed various milestones.  The additions have not been affected by the stock price of the moment, a rather silly way to make one's investment decisions with beasts of this nature.

Strategic Positioning of Clean Seed

When searching for potential investments in agricultural equipment manufacturers, I looked for, among other things, products which "fitted" best with emerging trends - in this case - the growing presence of larger farming operations.  The CX-6 Smart Seeder is clearly aimed at this market.  Read this. (You can drill down more by clicking on the links internal to the article.)

https://www.farm-equipment.com/articles/13828-deu

A New "Advance" in Nuclear Weaponry Poses a New Threat to Russia ... and everyone else

The U.S. has developed a new technology for fusing its nuclear warheads.  In brief, it enables the more accurate delivery of warheads over targets with the result that it has reduced the number of warheads required to neutralize hardened targets such a missile launch sites and control centres.

This has major consequences as it would appear that a "first strike" by the U.S. can be far more devastating ... and potentially, more "attractive" for those with the mentality of Dr. Strangelove.

It is also important to recognize that with the advance positioning of American nuclear submarines, delivery times have been reduced.  This is aggravated by the fact that Russian technology for the detection of incoming missiles provides only a fifteen minute window from the point of detection to the time of impact.  (The Americans have an advantage in that they have a satellite array which provides a thirty minute window.)

The following article provides a chilling portrait of this scenario.  It does not mention the growing capacity of the U.S. with respect to missile interception.

http://thebulletin.org/how-us-nuclear-force-modernization-undermining-strategic-stability-burst-height-compensating-super10578

The bottom line is that decision-making time for responses to perceived threats on the part of Russian operatives has been compressed.  The consequences of these decisions are probably more monumental than at any time in history.

Wednesday, 15 February 2017

Value of the "Long View"

Over time, I've come to appreciate the rewards associated with taking the "long view".  In short, it's all about selecting great companies and holding positions in them for the long term.

In selecting potential investments, I generally look for the following characteristics:

  • solid management: experienced in the field of endeavour; successful track records, ethical and unblemished by scandal; working in the interest of share owners
  • solid balance sheets: little debt; strong cash flows; good ROI
  • understandable business model 
  • competitive advantage
  • an enduring market for the company's products/services
As to the long term, I am patient with respect to an entry point for my investments.  As Herr Buffet would opine, it's about waiting for the "fat pitch". Some people may contend that this is akin to "market timing" i.e. trying to anticipate the direction of the market.  

I do not.  Sometimes, market sentiment results in widespread market declines based on fear of loss.  If anything, a study of historical price trends shows that companies with the above-noted attributes are very resilient: they eventually recover and prosper to the delight of investors who invested when others were paralyzed by uncertainties of the day.  

I have the sense that market valuations are getting rather lofty in today's environment: that optimism of the Trump effect is causing markets to rise in an unwarranted manner.  I am slowly building a nest egg and am prepared to wait for markets to correct.  I believe that the chaos in Washington is going to spill over into the markets.  Markets will become quite volatile and will present opportunities for investors who are positioned and prepared to profit from volatility.   

This post was stimulated by the following presentation.   


Saturday, 7 January 2017

Wonderful Piano Music from Argentina

Argentina has produced some wonderful composers, but they are not well known outside the country.  They should be.

Here are two of my favourite compositions.  You can play them for years and still discover new elements.  And they're great for the soul.

Alberto Ginestera (1916 - 1983) is/was one of Argentina's national treasures.

The Danza de la moza donosa  is one of his most haunting compositions.  One of the beauties of this music is that it places a great onus on the performer to get to the soul of the music.  The first interpretation comes from the mind of Daniel Barenboim.   The second is by Martha Agerich, a close friend of Barenboim and a frequent musical partner on stage.  Her tempo is a bit quick for my liking but the dynamics are fabulous.  Of the interpretations, the third appeals to me the most.

Danza de la moza donosa

Danza de la moza donosa

Danza de la moza donosa

And then, there's this: sublime:

https://www.youtube.com/watch?v=C1PsLjSfMoE

Astor Piazzolla is better known, an exponent of the nuevo tango.  For many years, I've been fascinated by his Milonga del Angel.

This version parallels the common piano score quite closely.  Slow in tempo, the pianist extracts some true beauty and meaning.
Milonga


This version is quite wonderful - elegant yet restrained.  Many other versions are "over the the top" and do a disservice to the music.  If anything, this one is a bit long, but why not dwell a while in musical heaven?
https://www.youtube.com/watch?v=vYdZBLGO0jA

The following version misses the essence of the piece - in my opinion.  You don't have to fill space with notes.  Sometimes silence makes a very elegant statement. This said, the performer has a real connection with the piano ... the notes floating off the strings are delicious.
Milonga

The good professor was trying to replicate the sound of the orchestra and came up short ... a misapplication of the instrument.  Here's the master himself ... it's one of several performances and interpretations.
https://www.youtube.com/watch?v=Z92szaC-Jds

My exploration of Argentine music continues.  One of my dreams is to take in a performance or two in the Teatro Colon, one of the best performance venues in the world.  Unfortunately it was closed when we were in Buenos Aires, the victim of a strike on the part of theatre staff.

Strikes are a regular feature of Argentine life. We also experienced a one day strike by garbage workers in BA and were lucky to have not been inconvenienced by another.

The day after we flew into Buenos Aires from the provinces, Aerolíneas Argentinas was hit by a strike.  The pilot and co-pilot were from separate unions and the co-pilot felt insulted by a comment from his seat mate during a pre-flight check.  Result = downed tools and no flights for the next few hours.  Had it been a day later, we would have been grounded as it took place on the same flight. One can only wonder what the impact (pardon the pun) would have been if the dispute had taken place while the plane was underway.  

Thursday, 5 January 2017

Stevia: An unanticipated result of a search for investments for drought resistant varietals

A few years ago, I established a very speculative position with S&W Seed Company (SANW - Q).

The investment originated as an outcome of a few conclusions I reached about agriculture, and forage crops in particular; namely:

  • the supply of arable land is declining globally
  • to an increasing degree, the quality of arable land has been degraded through inappropriate irrigation techniques which have led to a hostile growing environment as a result of high soil salinity
  • there will be a premium on water-efficient crops for at least three reasons:
    • an absolute reduction in the quantity, reliability, and quality of water - the result of more frequent and more prolonged droughts, and the reduced availability of groundwater as a result of ground water mining
    • increased competition for water e.g. the highest and best use is for urban and industrial consumption
    • increased costs (in light of the foregoing, an increased price is being placed on water which heretofore was often heavily subsidized by government)
Least one think that these are "third world" issues, one need only look at the current state of almond growing in California.  It has been a disaster and likely as not, the implications will be notable for other crops. https://newrepublic.com/article/125450/heres-real-problem-almonds

I tried to look for "pure plays" for this theme, for example:
  • more efficient irrigation and other ways of conducting agriculture in arid environments
  • indoor agriculture
  • alternative crops
I concluded that a promising area would be the breeding of more water-efficient crop varieties for the following reasons
  • it offers an opportunity for a "pure play"
  • it is a "space" where small entities can compete 
  • the upside can be significant in the event that a company is successful in bringing a product to market, especially if taken over by a larger entity (larger companies don't often have the agility to develop new technologies and accordingly, have corporate models which look for take-overs in order to expand their product offerings).
My research drew me to S&W Seed Company.

S&W provides expertise in agricultural breeding, production and processing for the alfalfa and stevia industries. Each day that passes, three major issues affect the world’s population. First, the population of the world continues to increase; secondly, the availability of arable land continues to decrease. This creates a dire set of circumstances for farmers trying to feed a population increasingly wanting a diet which includes many of the foods that alfalfa hay, the “queen of forages,” supports, including milk, cheeses and beef. Third, the rates of obesity, diabetes and other health-related issues continue to rise around the world, much of which has been attributed to the over-consumption of sugar. A natural alternative is needed in the marketplace, and S&W believes that alternative is Stevia. S&W Seed Company is capitalizing on these three very important trends to help farmers combat the challenges of today, while keeping an eye on providing sustainable solutions for tomorrow.
http://swseedco.com/about-us/

For that reason, I was prepared to sit back and await the results of my bet, knowing that it might be a decade before the investment bore fruit.

My investment thesis was simple:

  • The company is focused on the development of seeds for drought-tolerant alfalfa.  Given the current pace of climate change and there will be a demand for more water efficient forage crops plants in light of water shortages/competition and higher soil alkalinity.  
As an added bonus, I discovered that the company was also focused on the development of improved varieties of stevia.  It may represent an unintended outcome of my original search: that stevia may present a better opportunity.  

As noted earlier, I am patient when investing in technology companies.  I am prepared to take on risk and to accept that the stock price will fluctuate wildly in response to the vagaries of the market.  

While I do not pay too much attention to the market action of the moment, I do focus on:
  • the honesty and transparency of management (for strategic reasons, however, many companies hold their cards close to their chests ... and I accept this)
  • progress with the product (on the premise that it meets a real need that the market is prepared to pay for it)
  • strategic alliances (this can take many forms: composition of the Board of Directors, relationships with other companies for marketing and distribution - things which lie outside the core competencies of the company but which are complementary to its activities
  • the development of income streams to offset operational costs
  • a consistent ability to secure financing
  • promising field trials, preferably overseen by objective and competent third parties
S&W has survived and is making progress.  It is boring: no major breakthroughs - just a steady slog with the occasional achievement.  Like many nascent enterprises, this company has had some false starts as it has explored pathways to grow in its economic niche.  The company has survived and learned.  It is the nature of these enterprises that success is ultimately built on sustained and compounded effort.  I am prepared to wait.  And I don't pay much attention to quarterly reports - they are inimical to ventures of this nature. 

With investments of this type, it is rare for companies to meet all of the above-noted conditions.  However, when they do, the results can be gratifying.  I took this approach several years ago with Questor Technology Inc. and was rewarded nicely with my first 10 bagger.  And to think that my original investment sank by more the 50 percent.  After a spectacular performance, the company tanked with the decline in the oil patch.  My thought is that there is still great potential with this company. It is resilient and nimble and the recovery of oil prices and a broadening scope of products holds the prospect of a return to good times.  It helps that the company has an excellent balance sheet and great management.  


Another observation:  With innovative companies, it is common for prices to peak shortly after an IPO.  The "story" rather than the realities of "performance" tends to dominate investor decisions.  It is common for prices to decline thereafter and to languish for years.  Tiny, technology-based innovators are fragile beasts BUT if they have a product that meets a real market need and have good management, their prospects of survival are enhanced.  While one can never get the timing "right" (i.e. buy at a low and sell at the peak), it often pays well to look at yesterday's darlings - to get beneath the botox and see if the teeth and bones are good.  S&W Seed Company may once again, return to the ballroom.  

In future posts, I will report on my search for investments along the theme of water efficiency and alternatives to sugar.  

Arotech - The Market Responds

NN ARBOR, Mich., Jan. 03, 2017 (GLOBE NEWSWIRE) -- Arotech Corporation (Nasdaq:ARTX) today announced the early termination of its employment agreement with Steven Esses, Arotech’s president and CEO and a member of the Board. Mr. Esses left the Company and resigned as a director of the Company and as an officer and director of all of the Company’s subsidiaries effective December 31, 2016. The early termination was by mutual agreement.
The market has reacted very positively to this announcement.

In December 2015, I presented my thesis for investing in Arotech:

I have a small position in Arotech http://www.arotech.com

It is was a speculative bet.  At the time of purchase my view was that the company had some assets of value; however, they were compromised by management. The share price declined, but I held on in the hope that the company would eventually see sunshine. 

It appears that a deep-pocketed investor is proposing to shake things up.


http://finanacialpassagemaker.blogspot.ca/2015/12/artotech-some-thoughts-to-consider-when.html

In the above-noted post, I also presented information about the CEO and President of Arotech.  Having experienced the depredations of a President who was hired without any knowledge of the business I was in, I know on a first-hand basis, how such people can derail the operations of an enterprise: employees soon learned not to speak their minds; strategic mistakes were made; the individual lost respect within the "community", employee turnover rates approached 30 percent annually (I was a "leaver"), etc.  He was finally booted out by the Board.  A few years on, the organization is prospering under new leadership.  I don't know if there is a direct parallel with Arotech - this cannot be known except by insiders.  

It usually takes time for change to be effected: delaying tactics of the company executives and the board members appointed by them have to be overcome; there may be legal obstacles, financial controls take time to be implemented and so on.  However, it appeared that Echo Lake Capital prevailed and that initial steps had been taken to turn the company around: 

http://finanacialpassagemaker.blogspot.ca/2016/04/update-on-arotech.html

It will now be a matter of concentrating on the financials to see if the full potential of investing in the company can be realized.

I normally do not invest in turnaround situations, but this one was too good to pass up.  It resonated with my personal experience.  Maybe history will repeat itself.

I will maintain my position.  The company is well positioned given the proclivities of the "new management" at the White House.